Timing is everything in Utah’s highly competitive commercial real estate market. It can make or break a deal. So when an investor is looking to obtain a prime piece of property, waiting on bank approval could mean watching a profitable opportunity slip away. Investors need speed. They need certainty. Neither is possible with traditional lending. Yet both are fundamental to hard money.
For new investors exploring hard money for the first time, an important factor is understanding the timeline. Securing a hard money loan in Utah is not necessarily difficult. But investors should understand timing so that they know how to leverage hard money to secure the most competitive deals.
Efficiency Is the Reason
Efficiency plays a significant role in hard money timing. Hard money lenders in Utah are private and direct lenders. They make approval decisions based primarily on asset value. As such, getting approval with a solid commitment in just a few hours is normal. Getting to closing in days is also fairly common.
Traditional lenders are far less efficient. Loans have to go through multiple layers of approval and underwriting before closing can be entertained. Their lack of efficiency is the direct cause of banks and credit unions needing 45-90 days to get deals done.
Step-by-Step: The Hard Money Timeline
Every hard money transaction is unique, even if an investor works exclusively with one firm, like Salt Lake City’s Actium Lending. But generally speaking, the timeline for hard money loans in Utah is as follows:
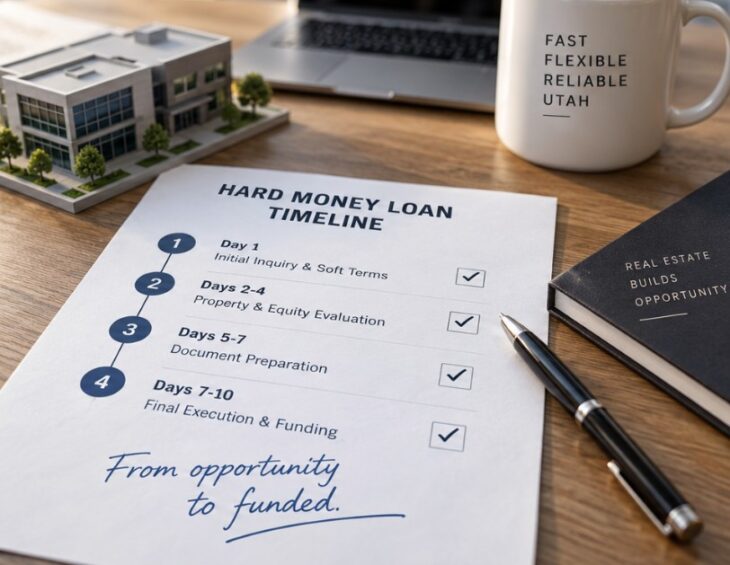
Day 1: Initial Inquiry and Soft Terms
The entire process begins with an inquiry and a straightforward overview of the deal. The borrower submits details about the property, including market location, current value, etc. A loan amount and the borrower’s exit strategy are also offered at this stage. Preliminary approval and non-binding term sheets are usually produced within 24 hours.
Days 2-4: Property and Equity Evaluation
With all the necessary information in hand, the lender begins the evaluation process. But instead of poring over years of personal financial statements and tax returns, Utah hard money lenders evaluate the property being acquired. Decision-makers look at:
- Property location and market viability
- The borrower’s existing equity position
- The proposed loan-to-value (LTV) ratio
- Overall asset strength
- Exit plan feasibility.
Although evaluation could take as long as three to four days, it doesn’t necessarily have to. Actium Lending has been known to complete this stage in a day or less.
Days 5-7: Document Preparation
The next step is to prepare documents and verify the title. The lender coordinates with local title and escrow teams to get the work done. An established equity structure and a clean title can speed things up significantly.
Days 7-10: Final Execution
The last step is loan execution. In essence, funding is wired to a title company or other entity, and the borrower proceeds with closing. In many cases, the title company acts as a trustee to facilitate what is legally recognized as a trust-deed transaction.
Actium Lending is quick to point out that hard money lenders in Utah can usually compress the entire timeline when necessary. If a 10-day timeline is adequate enough to secure the investor’s deal, things can remain a bit more relaxed. But if a shorter timeline is in play, lenders can usually get things done in 3-5 days.
When time is of the essence – which is often the case in commercial real estate transactions – hard money is the funding option of choice. Hard money lenders in Utah and elsewhere eliminate the uncertainty while providing the fast cash investors rely on.